Imagine two companies operating in the same sector, each reporting an "operating profit" in its annual report. The comparison looks easy, but it is actually misleading: each company calculated the figure in its own way, excluding some items and adding others. This is exactly the problem that the international standard IFRS 18 was designed to solve.
In this article, the team at Dar El Khebra Accounting & Auditing explains the key elements of the new standard, how the statement of profit or loss will change, and what your company should start doing now, ahead of the effective date.
What is IFRS 18 and when does it apply?
In April 2024, the International Accounting Standards Board (IASB) issued IFRS 18 "Presentation and Disclosure in Financial Statements" to replace IAS 1.
- Mandatory effective date: Annual periods beginning on or after 1 January 2027.
- Comparative figures: Applied retrospectively, so 2026 figures must be restated under the new structure.
- What does not change: Recognition and measurement rules. Net profit and total equity stay the same; what changes is presentation, classification and disclosure.
Why was IAS 1 replaced?
IAS 1 gave companies wide flexibility in presenting their results, which created three main problems for investors and analysts:
- No consistent structure for the income statement: Companies calculated "operating profit" in many different ways, even within the same sector.
- Adjusted measures without transparency: Such as "adjusted EBITDA", presented in press releases and investor presentations without explaining how it is calculated.
- Inappropriate aggregation or disaggregation: Combining different material expenses in a single line, or overloading readers with minor details.
Change one: five mandatory categories and two new subtotals
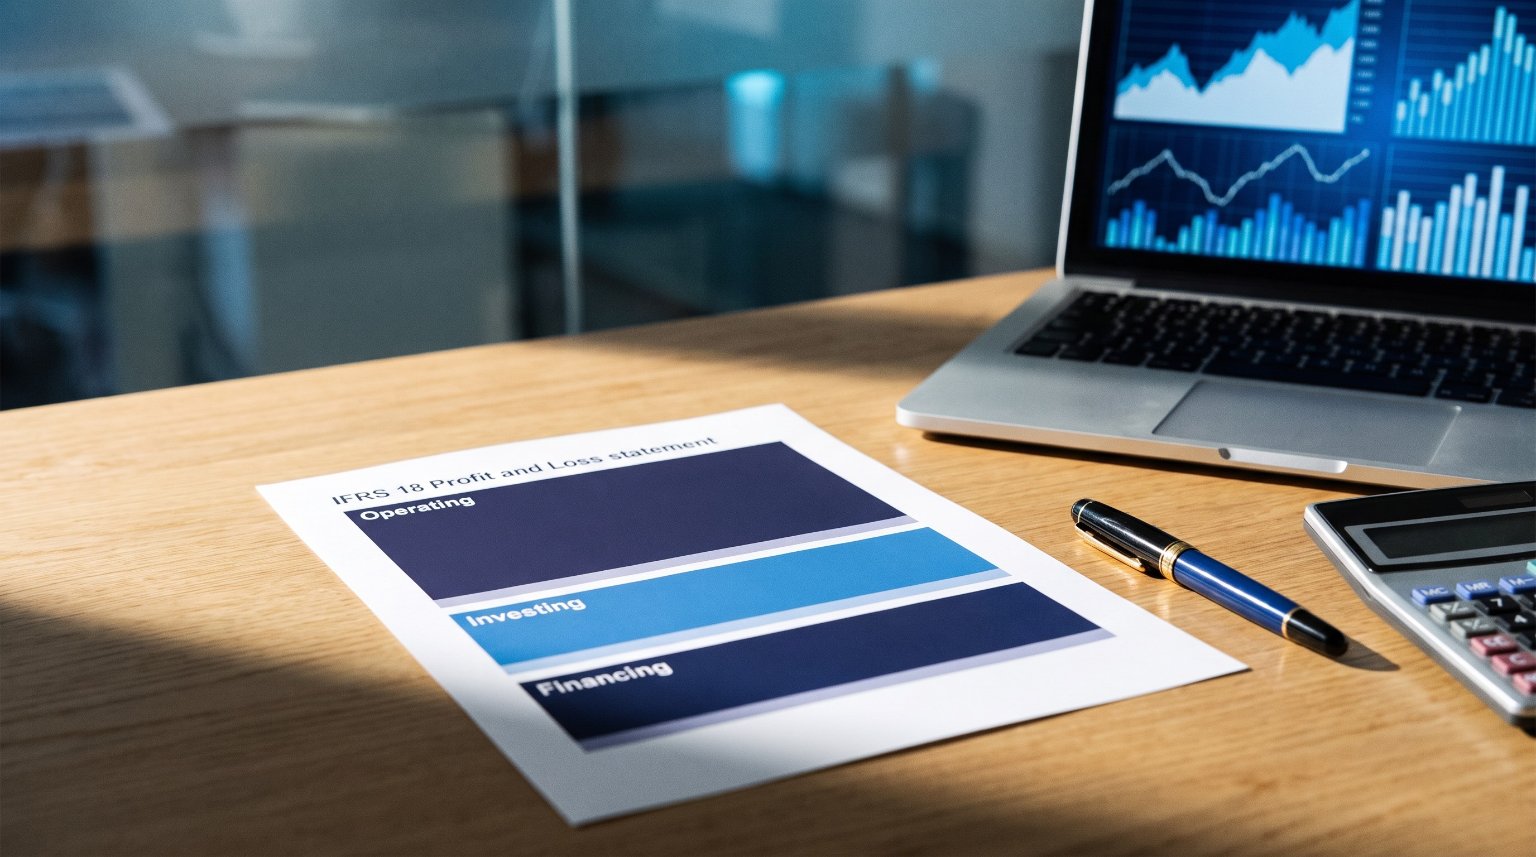
The standard requires all companies to classify income and expenses in the statement of profit or loss into five categories:
| Category | What does it include? |
|---|---|
| 1. Operating | The "residual" category: everything not classified in the other categories, including non-recurring or unusual items |
| 2. Investing | Returns from assets generating independent returns (investment property, equity investments), cash and cash equivalents, and the share of profit of associates and joint ventures |
| 3. Financing | Interest on loans and bonds, and interest on other liabilities such as lease liabilities (IFRS 16) and employee benefits (IAS 19) |
| 4. Income taxes | Current and deferred tax expense under IAS 12 |
| 5. Discontinued operations | Results of discontinued operations, net of tax, under IFRS 5 |
Two mandatory subtotals are derived from these categories:
- Operating profit or loss: The net result of the operating category. No operating expense may be excluded from it, even if described as "unusual" or "non-recurring", such as restructuring costs or fines.
- Profit before financing and income taxes (PBFIT): Operating profit plus the results of the investing category; it measures the return on the company's assets independently of how they are financed.
The golden rule: IFRS 18 does not change your net profit, but it changes the path the reader takes to reach it.
Classification cases that need attention
- Expected credit losses (ECL): On trade receivables they are classified as operating, while on bond investments and loans to third parties they are classified as investing.
- Foreign exchange differences: Follow the category of the underlying item: differences on customers and suppliers are operating, and on bank loans are financing.
- Leases (IFRS 16): Depreciation of the right-of-use asset is operating, and interest on the lease liability is financing.
- Banks and insurers: Special rules apply; most notably, interest on lending and deposits is classified as operating because it is the main business activity, and PBFIT is not presented.
Change two: management-defined performance measures (MPMs) under audit
This is the most significant development in the standard. The adjusted measures management uses to communicate with the market now become part of the audited financial statements. A measure is an MPM if it meets four cumulative conditions:
- It is a subtotal of income and expenses.
- It is used in public communications outside the financial statements (management reports, press releases, investor presentations).
- It reflects management's view of the performance of the entity as a whole.
- It is not a subtotal specified or excluded by the standards, such as gross profit, profit before tax, or operating profit before depreciation, amortisation and impairment.
It must then be disclosed in a single note that includes: why it is used and how it is calculated, areconciliation to the most directly comparable defined subtotal, and thetax effect and the effect on non-controlling interests for each reconciling item separately.
Change three: clearer rules on aggregation and disaggregation
The standard sets two principles: aggregate items with similar characteristics to avoid cluttered statements, and disaggregate items with different characteristics so that material information is not obscured. If a company presents its expenses by function (cost of sales, selling and distribution, administrative), it must disclose five items by nature in the notes:
- Depreciation
- Amortisation
- Employee benefits
- Impairment losses
- Inventory write-downs
Practical example: what does the income statement look like under IFRS 18?
Consider a manufacturing and trading company. This is how its statement of profit or loss is presented under the new structure (amounts in USD):
| Line item | Amount | Category |
|---|---|---|
| Revenue | 350,000 | Operating |
| Cost of sales, selling and development expenses | (235,000) | Operating |
| General and administrative expenses | (16,500) | Operating |
| Foreign exchange gains on trade receivables | 2,500 | Operating |
| Operating profit | 101,000 | Mandatory subtotal |
| Rental income from investment property | 12,000 | Investing |
| Share of profit of associates | 6,000 | Investing |
| Interest income on bank balances | 1,500 | Investing |
| Profit before financing and income taxes (PBFIT) | 120,500 | Mandatory subtotal |
| Interest on loans and bonds | (8,000) | Financing |
| Interest on leases (IFRS 16) | (2,000) | Financing |
| Net interest on employee benefits (IAS 19) | (1,500) | Financing |
| Foreign exchange losses on bank loans | (3,500) | Financing |
| Profit before income tax | 105,500 | |
| Income tax expense | (20,000) | Income taxes |
| Profit for the year | 85,500 |
Note that rental income from investment property and the share of profit of associates, which many companies used to include in their operating results, have been moved compulsorily to the investing category. Interest on employee benefits has also moved from administrative expenses to financing. Even so, net profit remains exactly the same.
Consequential amendments to other standards
- IAS 7 (Statement of Cash Flows): The indirect method starts from "operating profit", with consistent classification of interest and dividends.
- IAS 33 (Earnings per Share): Additional earnings per share may only be disclosed if the numerator is a subtotal defined by the standard or a disclosed MPM.
- IAS 34 (Interim Financial Reporting): The new structure and MPM disclosures extend to quarterly statements from the first year of application.
Does IFRS 18 apply in Egypt?
Companies in Egypt apply Egyptian Accounting Standards (EAS), which are close to IFRS but not identical, so IFRS 18 does not automatically apply to financial statements prepared under Egyptian standards. However, the standard directly affects companies that prepare their statements or group reporting under IFRS, such as subsidiaries of foreign or Gulf groups and companies dealing with international investors or lenders. Following the standard now gives any company an early start on any future development of Egyptian standards.
A 5-step readiness roadmap
- Gap assessment: Identify differences between current presentation and IFRS 18 requirements.
- Reclassification matrix: Map every trial balance account to one of the five categories, documenting the rationale.
- MPM governance: Identify externally reported measures and prepare reconciliations and tax-effect calculations.
- ERP development: Adjust the chart of accounts to generate the categories and the five expenses by nature automatically.
- Restating 2026 figures: Prepare comparative figures early and confirm that net profit is unchanged.
Quick checklist for the finance team
- ✔ Are all income and expenses classified into the five categories without exception?
- ✔ Are operating profit and PBFIT calculated and presented with the correct labels?
- ✔ Have all adjusted measures used in investor presentations and press releases been identified?
- ✔ Have reconciliations been prepared with the tax effect and non-controlling interest effect for each item?
- ✔ Does the disclosure include the five expenses by nature where expenses are presented by function?
- ✔ Have 2026 figures been reclassified with net profit and equity unchanged?
How can Dar El Khebra help?
Drawing on its expertise in audit, tax and advisory, Dar El Khebra's partner team provides integrated support to companies transitioning to IFRS 18:
- Designing accounting reclassification matrices
- Developing the chart of accounts in ERP systems
- Preparing and reviewing performance measure (MPM) disclosures
- Reviewing 2026 comparative financial statements
2027 effectively starts now, because 2026 figures are the comparatives. Contact Us or message us on WhatsApp at +20 100 086 7183 to start your gap assessment.